
Opening a Corporate Bank Account in Spain: A Step-by-Step Guide for Businesses
Navigating the process of opening a corporate bank account in Spain can be complex for foreign businesses and entrepreneurs. This comprehensive guide provides a step-by-step breakdown, covering essential requirements, regulatory considerations, and practical tips to ensure a smooth and efficient setup.
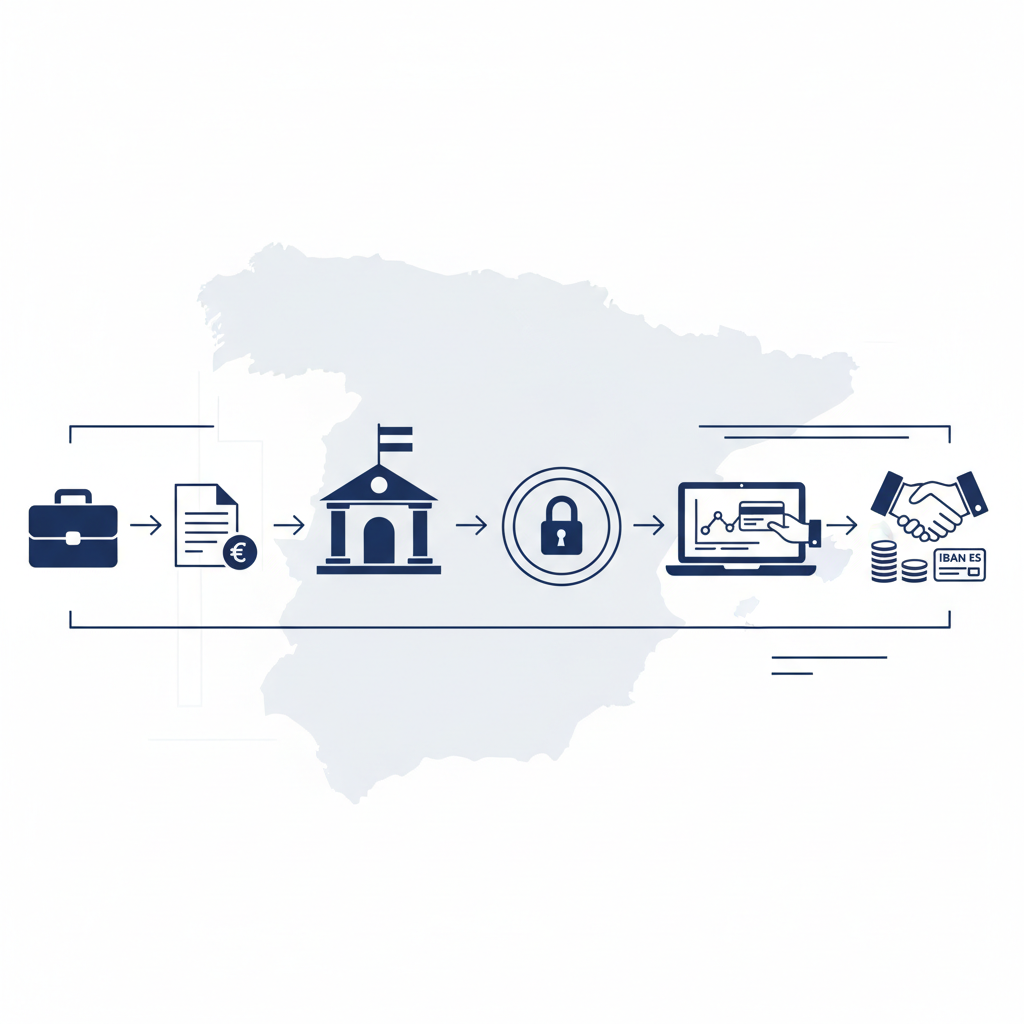
Opening a Corporate Bank Account in Spain: A Step-by-Step Guide for Businesses
Spain, with its vibrant economy, strategic location, and membership in the European Union, presents an attractive destination for international businesses looking to expand their operations. Establishing a local presence often necessitates opening a corporate bank account, a crucial step for managing finances, conducting transactions, and ensuring compliance with Spanish regulations. While the process can appear daunting, especially for non-residents, understanding the requirements and following a structured approach can streamline the experience significantly. This guide aims to demystify the process, offering actionable insights for entrepreneurs and companies.
The Importance of a Spanish Corporate Bank Account
A corporate bank account in Spain is more than just a convenience; it's a fundamental requirement for legal and operational functionality. It facilitates local payments, receipt of income, payroll processing for Spanish employees, and tax compliance. Without a local account, businesses face significant hurdles in managing day-to-day operations, often incurring higher transaction fees and experiencing delays with international transfers. Furthermore, having a Spanish bank account enhances a company's credibility and demonstrates a serious commitment to its operations within the country, which can be beneficial when dealing with local suppliers, clients, and regulatory bodies. It also simplifies the process of obtaining local financing or credit facilities should the need arise.
Key Requirements and Documentation
Opening a corporate bank account in Spain is subject to stringent anti-money laundering (AML) and know-your-customer (KYC) regulations. Banks will require a comprehensive set of documents to verify the identity of the company, its beneficial owners, and its legal representatives. While specific requirements may vary slightly between banks, the core documentation generally includes:
- Company Documentation:
- NIE (Número de Identificación de Extranjero) for Non-Resident Directors/Shareholders: This is an identification number for foreigners, essential for any financial transaction in Spain. Non-resident directors or beneficial owners will need to obtain one.
- CIF (Certificado de Identificación Fiscal) for the Company: This is the company's tax identification number, equivalent to a TIN or EIN. It is obtained from the Spanish Tax Agency (Agencia Tributaria) once the company is officially registered.
- Company Bylaws (Estatutos Sociales): The foundational document outlining the company's structure, purpose, and operational rules.
- Certificate of Incorporation (Escritura de Constitución): The official document proving the company's legal existence, registered with the Commercial Registry (Registro Mercantil).
- Power of Attorney (Poder Notarial): If a representative is opening the account on behalf of the company, a notarized power of attorney detailing their authority is required.
- Proof of Registered Office: A lease agreement or utility bill confirming the company's registered address in Spain.
- Director and Shareholder Documentation:
- Passport or National ID Card: Valid identification for all directors and significant shareholders (typically those holding 25% or more of the shares).
- Proof of Address: Recent utility bill or bank statement (usually within the last three months) for each director and significant shareholder.
- Curriculum Vitae (CV) or Professional Profile: Some banks may request this to understand the professional background of key individuals.
- Business Plan: A concise overview of the company's activities, expected turnover, and the purpose of the bank account. This helps the bank understand the nature of the business and assess risk.
- Source of Funds Declaration: Banks may require documentation to verify the origin of initial deposits, especially for larger amounts, to comply with AML regulations.
All foreign documents must be officially translated into Spanish by a sworn translator (traductor jurado) and, in some cases, apostilled to ensure their legal validity in Spain. It is advisable to prepare these documents well in advance to avoid delays.
The Step-by-Step Process
- Obtain NIE and CIF: Before approaching any bank, ensure all non-resident directors and beneficial owners have their NIEs, and the company has its CIF. This is a prerequisite for almost all financial and legal activities in Spain.
- Choose a Bank: Spain has a robust banking sector with several major players, including Santander, BBVA, CaixaBank, Sabadell, and Bankinter. Research different banks to compare their corporate offerings, fees, online banking capabilities, and customer service. Some banks are more accustomed to dealing with international clients than others. Consider factors like branch network, English-speaking staff, and digital services.
- Schedule an Appointment: Once you've shortlisted a few banks, contact them to schedule an appointment with a corporate banking advisor. It's often beneficial to speak with multiple banks to find the best fit for your business needs.
- Submit Documentation: Attend the appointment with all the required original documents and their sworn translations. The bank representative will review these documents, verify identities, and guide you through the application forms. Be prepared to answer questions about your business activities, expected transaction volumes, and the purpose of the account.
- Due Diligence and Approval: The bank will conduct its internal due diligence process, which can take anywhere from a few days to several weeks, depending on the complexity of the company structure and the completeness of the documentation. During this period, the bank may request additional information or clarification.
- Account Activation: Upon successful completion of due diligence and approval, the account will be activated. You will receive your account number (IBAN), details for online banking access, and any associated debit or credit cards. Initial deposits can then be made.
Costs, Timelines, and Practical Considerations
Costs: Opening a corporate bank account itself typically does not incur a direct fee, but businesses should be aware of associated costs:
- Account Maintenance Fees: Most Spanish banks charge monthly or quarterly maintenance fees for corporate accounts, which can range from €10 to €50 or more, depending on the services included.
- Transaction Fees: Fees for international transfers, ATM withdrawals, and certain payment services.
- Card Fees: Annual fees for corporate debit or credit cards.
- Document Translation and Apostille Fees: These can add up, especially if many documents require official translation.
Timelines: The entire process, from gathering documents to account activation, can take anywhere from 2 to 6 weeks, sometimes longer for complex cases or if documents are incomplete. Obtaining the NIE and CIF can add to this timeline if not secured beforehand.
Practical Considerations:
- Non-Resident Accounts: If the company is not yet fully registered in Spain or if the directors are non-residents, some banks may initially offer a non-resident account (cuenta de no residente). This can be a temporary solution until all Spanish legal requirements are met, after which it can be converted to a resident corporate account.
- Online Banking: Ensure the chosen bank offers robust and user-friendly online banking services, as this will be crucial for managing your finances remotely.
- English-Speaking Support: For international businesses, having access to English-speaking banking advisors can significantly ease communication and problem-solving.
- Initial Deposit: Some banks may require an initial minimum deposit to activate the account. Inquire about this requirement during your initial conversations.
- Ongoing Compliance: Banks continuously monitor transactions and may periodically request updated information to ensure ongoing compliance with AML and KYC regulations. Maintain accurate records and respond promptly to such requests.
Conclusion
Opening a corporate bank account in Spain is an essential step for any business looking to establish a foothold in the Spanish market. While the process demands careful preparation and adherence to regulatory requirements, it is a manageable undertaking with the right approach. By understanding the necessary documentation, selecting a suitable banking partner, and diligently following each step, businesses can successfully set up their financial infrastructure in Spain. This foundational element will not only ensure operational efficiency and legal compliance but also pave the way for sustained growth and success within the dynamic Spanish economy. Proactive planning and attention to detail are paramount to a smooth and efficient account opening experience.


